Home Purchase
Financing your dream home anywhere in Canada. Competitive rates from 50+ lenders.
Private & Commercial Mortgage Specialist
When the bank says no, Sasha finds a way. Private lending, commercial mortgages, and self-employed solutions for complex files — structured to close, and designed to move fast.
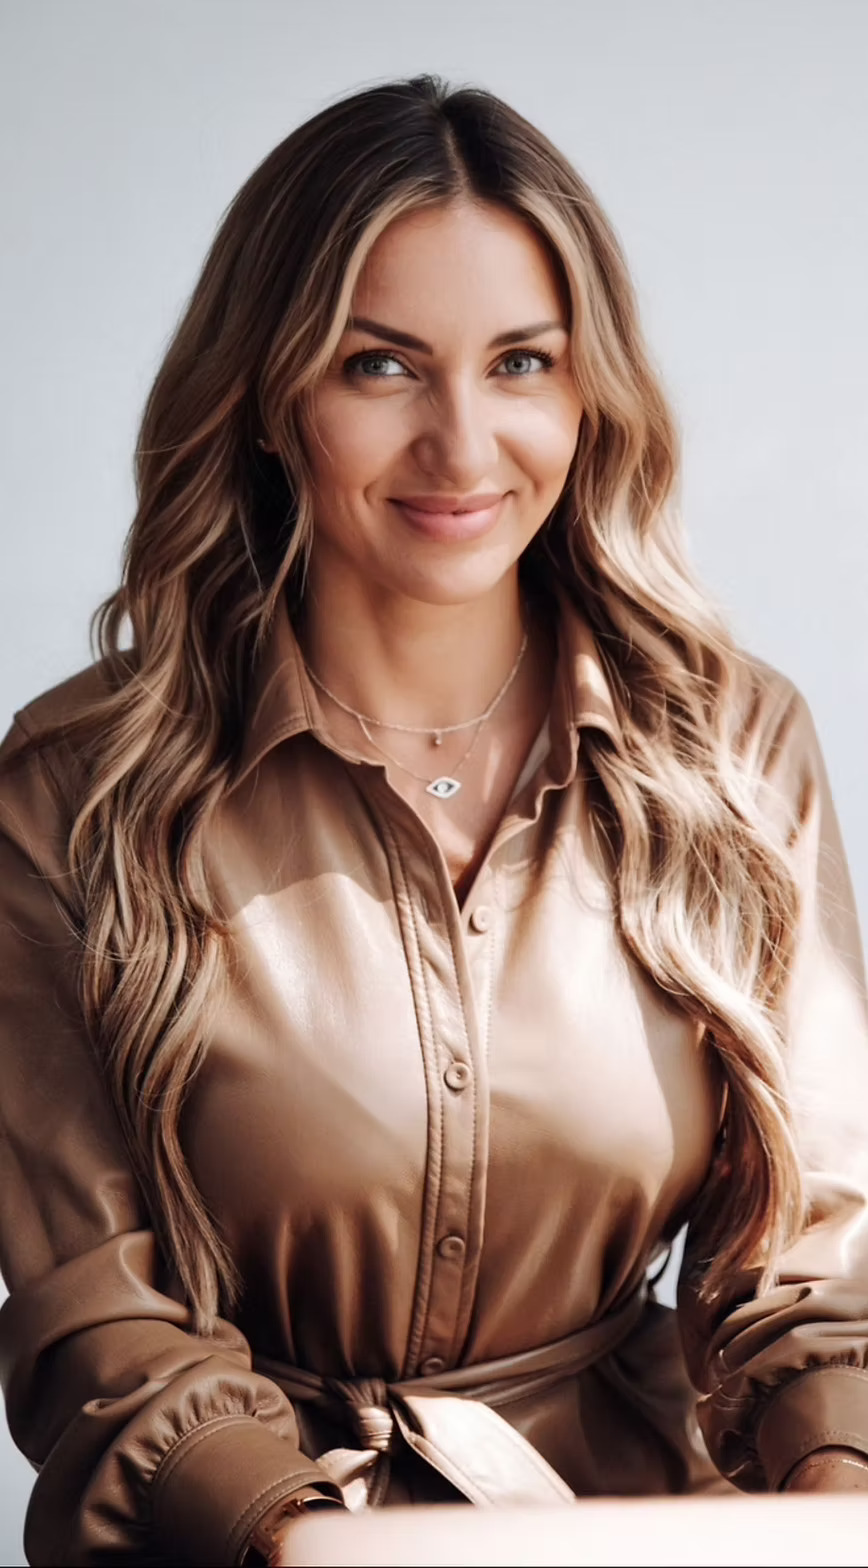
"I understand the complexities of the mortgage market and am here to guide you every step of the way."
"I am here to alleviate your frustrations and turn your dreams into keys." — Sasha Idema • Vancouver Mortgage Broker
About Sasha
Navigating Vancouver's real estate market is complex. Whether you are a first-time buyer in North Vancouver, an investor refinancing in Richmond, or a self-employed professional in Yaletown, I bring deep expertise in the Metro Vancouver lending landscape to every client relationship.
I specialize in assisting individuals and investors in the private, commercial, and industrial sectors secure mortgages that align with their goals and financial aspirations — including clients other brokers turn away.
What I Offer
From first-time buyers to complex commercial files — private, self-employed, and specialty mortgage solutions tailored to every situation across Canada.
Financing your dream home anywhere in Canada. Competitive rates from 50+ lenders.
Access your home equity, reduce your rate, or consolidate debt. Smart refinancing strategies anywhere in Canada.
Don't auto-renew with your current lender. I shop across 50+ lenders at renewal to make sure you always have the best available rate.
Rental properties, multi-family units, commercial acquisitions. Structured financing for real estate investors anywhere in Canada.
Stated income and alternative documentation programs for entrepreneurs, contractors, and incorporated professionals — across Canada.
Guiding first-time buyers through every step — FHSA, FHBP, CMHC insurance, and the full path to keys in hand, anywhere in Canada.
Specialty Mortgages
Sasha Idema is a licensed mortgage broker (BCFSA Lic. #154371 • Alberta Lic. #00132955) with Mortgage Architects in West Vancouver. She arranges private, commercial, self-employed and residential mortgages across Metro Vancouver, BC and Alberta, with access to 50+ lenders. These guides explain how each type works, what it typically costs and how to qualify.
Typical rates, fees and loan-to-value limits in BC, and when a private first or second mortgage makes sense.
Read the guideHow lenders assess industrial, retail, mixed-use and multi-unit property, from loan-to-value to debt service coverage.
Read the guideThe documents lenders want, the three ways to qualify, and how to strengthen your application.
Read the guideHow It Works
A streamlined, transparent process designed around your timeline — from initial application to closing day in Greater Vancouver.
Complete our secure application in minutes. No obligation, no credit pull until you're ready to proceed.
I assess your situation, identify the right lenders, and present you with a tailored mortgage strategy.
I negotiate with lenders on your behalf to secure the best available rate and terms for your situation.
Sign, fund, and get your keys. I'm with you every step — and here for renewals and referrals for life.
Client Stories
"A true professional and solution provider. Sasha was extremely proactive, went above and beyond in helping us secure our financing. I would definitely recommend her to friends and family."
"Sasha Idema is super professional and went out of her way to make this happen for my partner and I. They looked at all possible options and fulfilled our dream of buying a house."
"Sasha didn't give up until she found the best solution for our mortgage needs. We are so thankful — we ended up purchasing our dream home when we thought it wouldn't be possible."
FAQ
Have a question not covered here? I'm available Monday to Saturday, 8am to 8pm to talk through your specific situation.
Ask Sasha DirectlyIn Canada, the minimum down payment is 5% on the first $500,000 of the purchase price and 10% on the portion from $500,000 up to $1.5 million. Homes priced at $1.5 million or more require at least 20% down. The same federal rules apply in BC, and a lender may ask for more depending on the property and your situation.
Absolutely. Self-employed borrowers can qualify through stated income programs or by providing T1 generals and NOAs. I specialize in self-employed mortgage solutions across Greater Vancouver and have access to lenders who understand non-traditional income structures.
A private mortgage is funded by private investors rather than a bank or credit union. It's ideal for borrowers who don't qualify for traditional financing — including those with credit challenges, non-traditional income, or unique property types.
Pre-approvals can often be completed within 24 to 48 hours. Full approvals typically take 3 to 5 business days depending on the lender and documentation provided. I work quickly to keep your offer competitive in Vancouver's market.
In most cases, no. Mortgage brokers are compensated by the lender, not the borrower. There are no direct fees to you for standard residential mortgages. If a fee applies (such as for certain private lending scenarios), I will always disclose this upfront.
I serve all of Greater Vancouver including Vancouver (all neighbourhoods), Burnaby, Richmond, Surrey, North Vancouver, West Vancouver, Coquitlam, New Westminster, and Langley. Remote clients across BC are also welcome.
Sometimes. On insured mortgages (less than 20% down), first-time buyers and buyers of newly built homes can choose up to 30 years, while other insured buyers are limited to 25 years. Many lenders also offer 30-year amortizations on uninsured mortgages with 20% or more down.
Typical market ranges are about 6% to 8% on a first mortgage and 8% to 12% on a second, plus a lender fee of roughly 1% to 3% and sometimes a broker fee. Private mortgages usually run 6 to 24 months. See the private mortgage guide for a worked example.
A commercial mortgage finances business or income property such as industrial, retail, office, mixed-use or multi-unit buildings. Lenders look at the property income and the borrower together, typically lend up to about 65% to 75% of value, and often want a debt service coverage ratio near 1.2. See the commercial mortgage guide.
A bank can only offer its own products. A broker compares many lenders, including banks, credit unions and alternative lenders, and can place files that a single bank would decline. For most standard mortgages the lender pays the broker, so you pay no direct fee.
Expect to provide photo ID, proof of income such as recent pay stubs, a T4 or Notice of Assessment, proof of your down payment and its source, and details of the property. Self-employed borrowers usually provide two years of T1 Generals and Notices of Assessment. See the self-employed mortgage guide.
Federally regulated lenders must confirm you could still afford your payments at a qualifying rate that is higher than your actual contract rate. It limits how much you can borrow, and the rules can change, so ask for your current maximum before you shop for a home.
A second mortgage is a separate loan registered behind your first mortgage that lets you borrow against your home equity without changing the first mortgage. It usually costs more than a first mortgage, so it tends to suit shorter-term needs such as a renovation, debt consolidation or a bridge to a refinance.
It is worth comparing. At renewal you can usually move to a different lender without a prepayment penalty, and a broker can compare offers instead of you accepting the renewal letter your current lender sends. Start about four months before your renewal date.
Ready to explore your options? I'm available Monday to Saturday, 8am to 8pm Pacific. Reach out and I'll respond the same day.
604.488.4434200-100 Park Royal S.
West Vancouver, BC V7T 1A2